How to Build an Emergency Fund Step by Step, Even From Small Amounts
Starting an emergency fund can feel daunting, but small, steady steps can build a cushion that makes surprises less stressful.
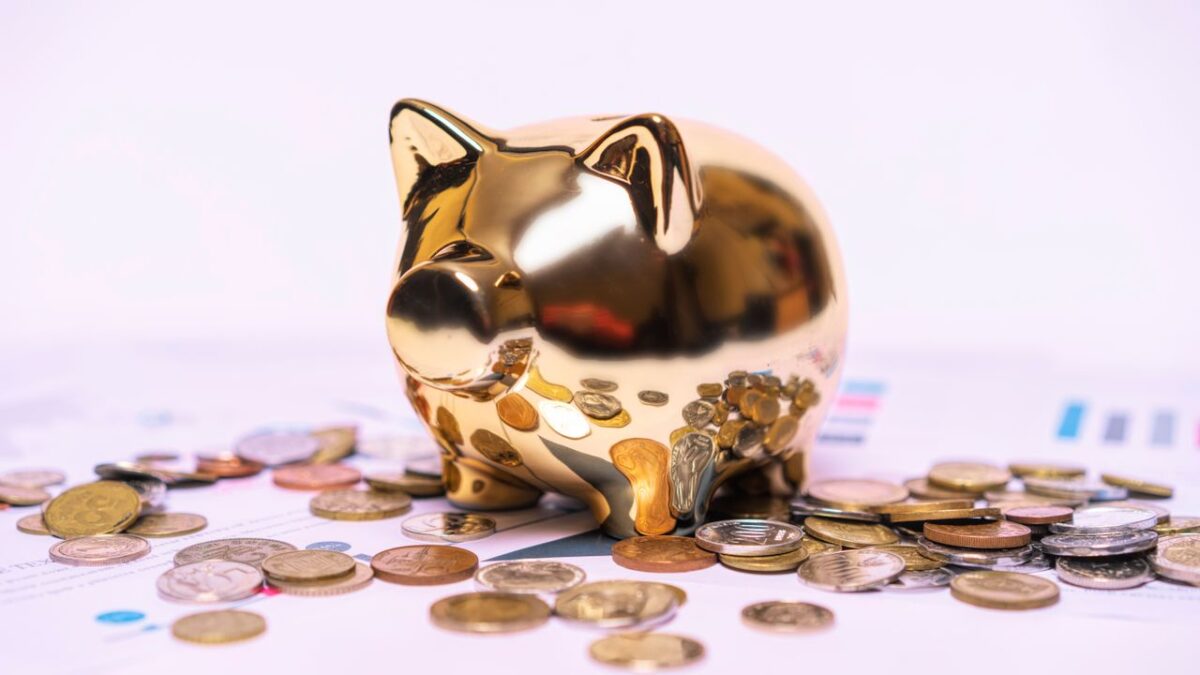 Photo: Atlantic Ambience / Pexels
A flat tire, a vet bill, or a sudden dip in work hours can turn an ordinary week upside down. An emergency fund is simply money set aside for moments like these, so you are not forced to scramble. Building one can feel overwhelming at first, but it does not have to happen all at once.
What matters most is getting started and keeping the habit going. Here is a step-by-step approach that works even when your budget feels tight.
Start With a Tiny First Goal
Skip the big number for now. Many people get discouraged by advice about saving several months of expenses, so begin with a small, reachable target. Something like one hundred dollars, or the cost of a typical car repair, is a great first milestone.
Hitting a small goal quickly gives you momentum. Once you reach it, set the next one a little higher and keep going.
Give the Money Its Own Home
Keep your emergency savings separate from your everyday checking account. When it all sits in one place, it is far too easy to spend it by accident. A separate savings account, ideally one that is easy to reach but not attached to your debit card, adds a helpful bit of friction.
Give the account a name that reminds you of its purpose. Calling it something like Rainy Day or Just in Case makes you think twice before dipping in for a non-emergency.
Automate Small, Regular Transfers
Willpower is unreliable, but automation is not. Set up a recurring transfer for a small amount on each payday, even if it is just five or ten dollars. Because it happens on its own, you will not have to decide each time whether to save.
If you can, raise the amount a little whenever your income goes up or a bill goes away. You will hardly notice the difference, but your balance will.
Find Money You Did Not Know You Had
Small windfalls can give your fund a boost without touching your regular budget. The trick is deciding ahead of time that a portion of them goes straight to savings.
- Move the cash you save from canceling a service you do not use.
- Put aside part of any birthday money, refunds, or side-job earnings.
- Sell a few unused items around the house and deposit the proceeds.
- Round up purchases to the next dollar and save the difference, if you like that method.
Know What Counts as an Emergency
Write down a short definition before you need it. Real emergencies are usually unexpected, necessary, and urgent, like a medical bill, an essential home or car repair, or a gap in income. A sale on a gadget or a weekend trip, however tempting, is not on that list.
If you do use the fund, do not feel guilty. That is exactly what it is for. Just make a plan to refill it, even if it takes a while.
Grow It at Your Own Pace
Once you have a starter cushion, you can aim higher. A common goal is to cover a few months of basic costs, such as housing, food, utilities, and transportation. Your own target depends on your situation, such as whether your income is steady or varies, and whether others rely on you.
There is no single right number, and no perfect timeline. Some months you will save more, and some months you will save nothing. What counts is that you keep coming back to it.
Over time, those small deposits add up to something that matters: the ability to handle a bad surprise with a little less worry. Start with whatever amount you can spare this week, set up that first transfer, and let the habit do the heavy lifting from there.